













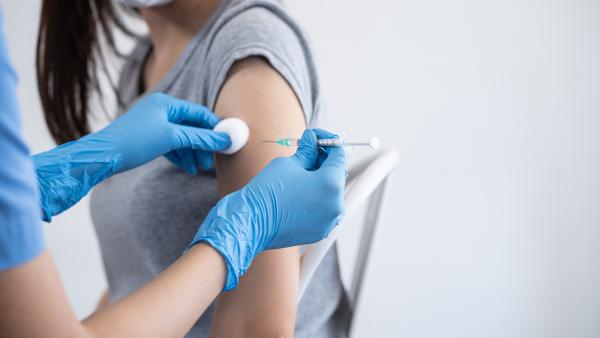
Around 20 million Brits receive a flu jab each year, with some employers choosing to pay for the cost of the vaccine for their staff ahead of the winter. Many employers see this as a value for money if it reduces the time that staff need to take off work for seasonal illnesses. But HMRC also saw it as a potentially taxable benefit, and until recently, the way in which the employer paid for the jab made a difference to the tax treatment for employee and employer.
Old rules
Prior to 5 April 2026, the tax rules were best suited to those who worked on the employer’s premises. The employer could, for example, pay for a medical professional to attend their premises and give employees their vaccine during the working day without tax consequences for employee or employer.
As working practices have changed, employers have moved to different ways of paying for flu vaccines – many have paid for them directly or given staff a voucher they can use to arrange their own vaccine appointment (such as at a local chemist). Others have asked employees to pay for their own flu jab and reimbursed the cost through their expenses claim.
As flu vaccines would normally cost far less than £50, where the employer paid for the vaccine directly, or gave the employee a voucher, their flu vaccine would have been exempt from tax as a trivial benefit. However, where the employee was reimbursed for their jab, it was not possible to rely on the trivial benefits exemption, as this does not apply to payments of cash. This meant that the reimbursement needed to be subject to PAYE and Class 1 National Insurance via the payroll, despite the relatively modest cost.
A new statutory exemption
The 2025 Budget made it much simpler for employers, as there is now a new statutory exemption for the cost of flu vaccines. As long as the vaccine is not provided under a salary sacrifice arrangement (where the employee gives up part of their salary to receive the vaccine), from April 2026 the cost of the flu vaccine is exempt from both Income Tax and National Insurance. This is regardless of whether the employer pays the costs directly, provides a voucher or reimburses the employer for the cost of the vaccine.
No change for other vaccines
When the exemption was introduced, the ATT suggested to the government that it may be worth expanding the scope of the new exemption, so that it could cover other vaccines that may benefit employees who are not eligible to receive one from the NHS, such as COVID vaccines.
At the moment, the scope of the exemption is limited to flu vaccines, so the previous rules will continue to apply if any other vaccines are paid. COVID vaccines normally cost more than £50, so even if the employer pays for a COVID vaccine the cost will be too high for it to be classed as a trivial benefit.
Time for employees to offer vaccines to staff?
As we are approaching the first winter where the new exemption applies, employers who have not previous offered staff a vaccine may now wish to do so. Although flu vaccines are generally inexpensive, the exemption does not have a cost limit, which will help employers if the cost of flu vaccines increases over time.
This article reflects the position at the date of publication shown above. If you are reading this at a later date you are advised to check that that position has not changed in the time since.
We regularly publish articles on a range of tax and wider topical issues which affect employers. If you wish to subscribe to our monthly Employer Focus e-newsletter, please contact us.